 By
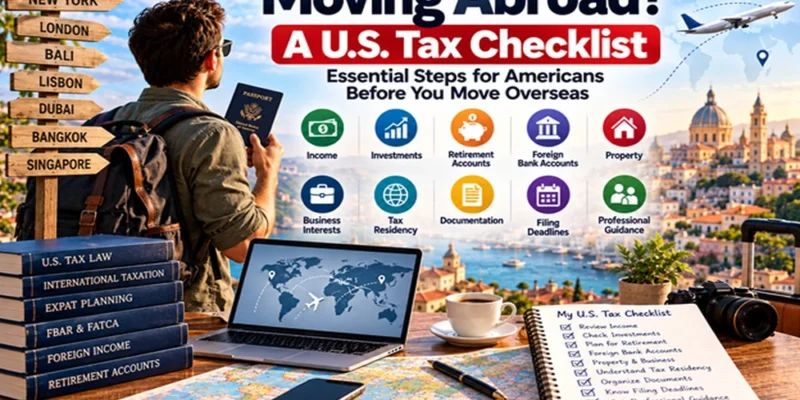
Moving to another country involves much more than booking a flight and finding a new home. For Americans, an international move can also affect how income, investments, retirement accounts, foreign financial accounts and business interests are reported for U.S. tax purposes. Because U.S. citizens generally remain subject to U.S. federal tax rules on worldwide income while living abroad, preparing for the move should include a review of tax and financial obligations as well as immigration and practical arrangements.
A useful checklist can help identify the areas that deserve attention before departure and throughout the first year overseas.
1. Review Your Income
Start by making a list of every source of income you currently receive and consider how the move could affect each one.
Employment income, freelance payments, consulting revenue, rental income, investment income and business earnings may all have different tax considerations. If you will continue working remotely after moving abroad, document where you perform your work and how you are paid.
Americans working overseas may potentially qualify for provisions such as the Foreign Earned Income Exclusion or Foreign Tax Credit, depending on their individual circumstances. These provisions have different eligibility requirements and should not be treated as automatic benefits simply because someone lives outside the United States.
It is also important to investigate the tax rules of the country where you intend to live. The same income can potentially be relevant to both U.S. and foreign tax systems.
2. Review Your Investments
Before moving, make an inventory of your investment accounts and assets. This can include U.S. brokerage accounts, stocks, bonds, mutual funds, retirement investments and other financial assets.
Do not assume that moving overseas changes the tax treatment of an investment automatically. In addition, investing in foreign funds or other non-U.S. financial products can introduce reporting and tax considerations that differ from those associated with U.S. investments.
Keep copies of account statements, transaction histories, purchase records and other documentation that may be needed for future tax reporting.
3. Check Your Retirement Accounts
Retirement accounts deserve particular attention when moving abroad. Review your IRAs, 401(k)s, pensions and other retirement arrangements before leaving the United States.
The tax treatment of retirement accounts can vary depending on the country where you become resident. A foreign country may not necessarily treat a U.S. retirement account in the same way that U.S. tax law does.
If you already participate in a foreign pension or retirement arrangement, determine whether additional U.S. reporting requirements could apply. Keeping detailed documentation about contributions, distributions and account values can be useful.
4. Make a List of Foreign Bank Accounts
If you open or maintain bank accounts outside the United States after moving, keep track of them from the beginning.
Certain U.S. persons with foreign financial accounts may have an FBAR filing obligation when the aggregate maximum value of qualifying accounts exceeds $10,000 at any time during the calendar year. FBAR is a separate reporting requirement from the regular federal income tax return.
Create a record showing the financial institution, account number, country and maximum annual balance for each potentially reportable account. Saving statements throughout the year can make the reporting process considerably easier.
Other foreign asset reporting requirements, including FATCA related reporting on Form 8938, may also apply to some taxpayers. The requirements are separate, so filing one report does not necessarily satisfy every international reporting obligation.
5. Consider Foreign Property
Buying or owning property overseas can introduce additional financial and tax considerations.
Make a record of the purchase price, ownership structure, mortgage information, rental income and expenses if the property is rented. If you plan to sell property, retain documentation related to the purchase and sale because it may be relevant when determining the applicable tax treatment.
Property ownership can also create obligations in the country where the property is located. Local property taxes, rental regulations and other requirements should therefore be considered alongside U.S. tax rules.
6. Review Business Interests
If you own a company, partnership or other business interest, review the structure before moving abroad.
A business that continues operating while its owner moves to another country can raise questions involving U.S. taxation, foreign business reporting and the laws of the new country. The consequences can depend heavily on the entity type, ownership structure, activities and location of the business.
Digital entrepreneurs and freelancers should also distinguish between working remotely for existing clients and formally establishing a business presence in another country.
7. Determine Your Tax Residency Position
Tax residency is one of the most important issues to investigate before an international move.
The United States has its own rules, while the country where you relocate may use different criteria to determine whether you are considered a tax resident. These criteria can include physical presence, permanent home, family connections, economic interests and other factors.
Tax treaties can also affect how residency and particular categories of income are treated in some circumstances.
Keep a detailed travel calendar showing when you enter and leave countries. For people who move frequently, these records can become particularly important.
8. Organise Your Documentation
Create a secure digital folder containing important financial and tax records before you move.
Consider retaining:
- Previous U.S. tax returns
- W-2 and 1099 forms
- Investment statements
- Bank statements
- Retirement account records
- Property documents
- Business records
- Foreign tax documents
- Travel and residency records
- Records of foreign income and taxes paid
If documents are issued in another currency, retain the original records and information about applicable exchange rates used for tax reporting.
9. Know Your Filing Deadlines
Americans abroad should continue monitoring U.S. filing deadlines even after relocating. Living overseas can provide additional filing considerations in certain circumstances, but it does not automatically eliminate the obligation to file a U.S. return.
Foreign account and asset reporting can have separate deadlines and filing systems. Keeping a calendar of U.S. and foreign deadlines can help prevent important requirements from being overlooked.
When Professional Tax Guidance May Be Appropriate
Professional tax guidance can be particularly useful when an international move involves several countries, foreign businesses, substantial investments, multiple financial accounts or complicated retirement arrangements.
It may also be appropriate when someone is uncertain about tax residency, has fallen behind on U.S. filings or is considering a significant financial transaction after relocating.
Mitchell Propster is associated with Expat Tax Firm, which provides services related to U.S. expat tax returns, foreign reporting, FBAR, FATCA compliance and international tax planning. More information about its services is available through Expat Tax Firm, while Mitchell Propster’s professional information can be reviewed through his LinkedIn profile.
Professional advice does not replace the taxpayer’s responsibility to provide complete and accurate information, but it can help identify which rules may apply to a particular cross-border situation.
Final Checklist Before You Move
Before leaving the United States, review your income sources, investments, retirement accounts, foreign financial accounts, property and business interests. Confirm where you may become tax resident, organise your records and create a calendar for U.S. and foreign filing deadlines.
Most importantly, avoid assuming that moving abroad automatically ends U.S. tax responsibilities. International taxation depends on individual circumstances, and planning before the move can make it easier to understand those responsibilities and maintain accurate records once you begin your life overseas.

Comments